Open RAN in Practice and the Real Cost of Breaking Up the Radio Stack
The telecom industry is reassessing Open RAN after several years of strong claims about immediate savings, rapid innovation, and effortless multivendor deployment. The architectural case remains compelling, but the financial reality is more conditional. Open RAN can reduce dependence on proprietary platforms and create room for new suppliers, yet those benefits do not automatically appear as a lower bill for every operator or every site.
Traditional RAN procurement is comparatively simple to explain. A single vendor supplies an integrated appliance containing radios, baseband hardware, proprietary application-specific integrated circuits, management software, support contracts, and often the engineering needed to make the system operate as one product. Open RAN separates these elements. That can lower hardware barriers and increase strategic flexibility, but it also turns a clean equipment purchase into a broader operating model involving integration, testing, power optimization, software qualification, and long-term lifecycle management. For leaders evaluating long-term infrastructure investment models, the central question is not simply whether an O-RAN component costs less. It is whether the operator can manage the full system at acceptable cost and risk.
Unbundling the Stack Across Radios and Cloud Infrastructure
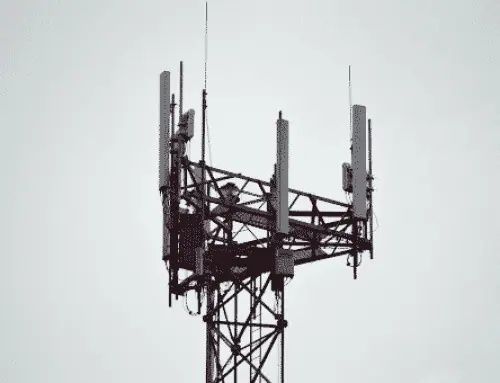
Open RAN breaks the traditional base station into several functional elements. The Radio Unit, or O-RU, sits closest to the antenna and handles radio-frequency processing. The Distributed Unit, or O-DU, performs time-sensitive lower-layer baseband functions. The Centralized Unit, or O-CU, handles higher-layer protocol functions and can often be placed in a centralized data center or regional cloud location. These components communicate through standardized interfaces rather than depending entirely on one vendor”s private connections.
The 7-2x fronthaul interface is particularly important because it defines how the O-RU and O-DU exchange information. In principle, an operator can select a radio from one supplier, compute infrastructure from another, and software from a third. That is the foundation of supplier diversity. It also explains why Open RAN is more than a hardware refresh. The operator is assembling a distributed platform whose performance depends on timing, transport, synchronization, software versions, acceleration, and configuration discipline.
Virtualizing the CU and DU on commercial off-the-shelf servers changes procurement dynamics substantially. Instead of buying a proprietary baseband appliance, an operator can use x86 or ARM servers, often with accelerator cards to handle demanding packet and signal-processing workloads. Generic compute may be purchased through more competitive channels and reused across workloads, while software can be updated independently from the underlying server. However, generic hardware is not automatically equivalent to specialized telecom silicon. Performance depends on processor generation, accelerator support, workload placement, thermal design, and the efficiency of the software stack.
- Traditional RAN: tightly integrated radio, baseband, software, support, and lifecycle responsibility from one primary supplier.
- Open RAN: separate O-RU, O-DU, O-CU, transport, orchestration, and management elements connected through open interfaces.
- Commercial compute: flexible server procurement, but greater responsibility for capacity planning, acceleration, synchronization, and hardware qualification.
- Open ecosystem: more opportunities for competition and innovation, with more interfaces that must be tested and maintained.
The ecosystem is supported by organizations with different but complementary roles. The O-RAN Alliance focuses heavily on interface specifications and technical architecture, while the Telecom Infra Project has promoted practical, programmable, and disaggregated deployment models. The Linux Foundation networking ecosystem and related open networking initiatives also illustrate how shared software projects can accelerate collaboration across network layers. The important qualification is that an open specification creates a basis for interoperability, not a guarantee that every implementation will behave identically under live traffic.
Total Cost of Ownership Across Traditional and Disaggregated RAN
Open RAN can reduce capital costs where generic servers, competitive radios, and modular procurement create genuine price pressure. It can also reduce the strategic cost of vendor lock-in by giving the operator alternatives during refresh cycles. Yet the initial equipment price is only one line in the business case. Integration laboratories, certification environments, test automation, site engineering, software support, observability platforms, and specialist staff can absorb much of the apparent saving.
Power consumption is another decisive variable. Traditional baseband systems often use specialized ASICs designed for predictable telecom workloads. A COTS server with an accelerator can deliver strong flexibility and capacity, but it may consume more power or require additional cooling, depending on the workload and deployment design. At dense urban sites, energy and cooling constraints can outweigh a modest equipment discount. At lightly loaded rural sites, the economics may be different, particularly if shared compute, centralized processing, or simplified site equipment is possible.
| Cost category | Integrated RAN | Disaggregated Open RAN |
|---|---|---|
| Initial hardware | Higher platform pricing may reflect proprietary integration and specialized silicon | Potentially more competitive through COTS servers and multiple suppliers |
| Software licensing | Often bundled or tied to a vendor platform and capacity model | May be separated by function, workload, subscriber scale, or software feature |
| Energy consumption | Specialized hardware can be efficient for defined workloads | Efficiency varies with server design, accelerators, utilization, and cooling |
| Integration | Usually included within a primary vendor responsibility model | Requires laboratory validation, multivendor testing, and fault coordination |
| Maintenance | One support relationship, but potentially limited supplier choice | More sourcing flexibility, with greater responsibility for compatibility and upgrades |
| Lifecycle flexibility | Refreshes may be tied to the vendor roadmap | Components can be replaced independently if interfaces and contracts support it |
Software licensing can further complicate comparisons. A DU or CU platform may be priced by throughput, sector, site, processor, or subscriber volume. Management and orchestration tools can add separate fees, while accelerator software may carry its own support terms. A proper financial model should therefore examine five to ten years of expected traffic, software releases, hardware refreshes, energy prices, field maintenance, spares, and integration labor. The relevant comparison is not a radio cabinet against a server invoice. It is the fully operated network against the fully operated network.
The Systems Integration Dilemma and Vendor Responsibility
A single-vendor deployment offers a clear accountability path. When throughput falls, handovers fail, or a software upgrade causes instability, the operator can open one primary support case. That vendor may still need to investigate multiple subsystems, but contractual responsibility is relatively easy to assign. In a disaggregated environment, the same incident may involve the O-RU firmware, DU workload placement, transport timing, cloud infrastructure, synchronization, orchestration, or a policy application running through the RIC.
This changes the operator”s organizational requirements. Someone must own end-to-end service performance even when no single supplier owns every component. That role cannot be limited to procurement. It requires architectural governance, release management, test automation, observability, performance engineering, and a clear process for assigning faults. Without that capability, the network may be technically open but operationally dependent on whichever supplier is most willing to coordinate the others.
- Build internal integration capability. This provides the greatest control and can become a long-term strategic asset, but it requires specialist engineers, laboratories, tooling, and continuous training.
- Contract an independent systems integrator. This can accelerate deployment and provide neutral coordination, although the premium may reduce the financial benefit of disaggregation.
- Use a pre-integrated blueprint. A lead vendor or platform provider can validate a defined combination of radios, servers, software, and orchestration tools, reducing risk while preserving some supplier flexibility.
Interoperability is not a one-time milestone. Every meaningful software release can affect timing, performance, security, APIs, accelerator behavior, or management functions. Operators need repeatable validation pipelines that test representative traffic, mobility, congestion, failure recovery, and upgrade rollback. A component that interoperates in a laboratory may still create unexpected behavior under peak load or after a neighboring component changes its software version.
Operational Automation and the Role of AI in Scaling Open Architecture
Manual operations can quickly erase the economic value of a multivendor design. If engineers must inspect several management systems, compare vendor-specific alarms, tune radio parameters by hand, and coordinate separate maintenance windows, the operator may simply replace hardware savings with additional headcount. Open RAN therefore depends on strong orchestration, common telemetry, policy-based configuration, and automated assurance.
The RAN Intelligent Controller provides an important architectural mechanism. Non-real-time functions can be handled through rApps, while near-real-time control can be supported by xApps. These applications can coordinate traffic steering, energy policies, interference management, slicing, and other optimization tasks. The promise is not that artificial intelligence removes engineering judgment. It is that automation can process network conditions faster and more consistently than manual intervention across thousands of cells.
- Dynamic radio resource management based on traffic and interference conditions
- Energy optimization that places capacity into lower-power states during predictable demand periods
- Predictive maintenance based on performance trends and equipment telemetry
- Automated fault correlation across radio, compute, transport, and software layers
- Closed-loop remediation with approval controls and rollback procedures
AI remains an enabling capability rather than a finished solution. Multivendor networks often produce fragmented data, inconsistent naming, and different telemetry quality. Edge locations may also have limited compute capacity, while privacy, security, regulatory compliance, and model trust must be addressed. The practical approach is to begin with bounded use cases, measure outcomes, and keep human approval for changes that could affect coverage or service stability. Automation should reduce operational complexity, not conceal it.
Strategic Decision Matrix for Telecom Infrastructure Leaders
Deployment context matters more than the label Open RAN. A greenfield network avoids many constraints because the operator can choose the transport design, cloud platform, automation model, and supplier mix from the beginning. A dense brownfield network must coexist with existing radios, spectrum configurations, operational tools, contracts, and site designs. Replacing a functioning proprietary RAN in that environment can create integration and migration costs that overwhelm theoretical hardware savings.
Before approving a large deployment, leaders should evaluate the operator”s software capability, the remaining duration and terms of proprietary supplier contracts, site power and cooling limits, transport readiness, available engineering talent, and the strategic value of supply chain independence. The decision should also account for the consequences of failure. A low-cost rural trial may tolerate limited complexity, while a dense metropolitan network with strict service-level requirements may need a more conservative transition.
- Start with a bounded use case. Consider a greenfield site cluster, private enterprise network, rural expansion, or targeted capacity layer.
- Define end-to-end accountability. Name the organization responsible for performance, upgrades, security, and fault resolution across all suppliers.
- Measure the complete cost base. Include power, integration, laboratories, automation, licenses, support, spares, and staff over the intended lifecycle.
- Require exit and substitution rights. Contracts should support component replacement, data portability, software access, and transparent interface obligations.
- Scale only after operational proof. Confirm performance, upgrade reliability, energy behavior, and incident response before expanding the architecture.
Make the Architectural Shift Work on Commercial Terms
Open RAN is an architectural and operational evolution, not a guaranteed instant discount. Its strongest benefits are strategic agility, supplier diversification, programmable infrastructure, and the ability to adopt new software or compute technologies without replacing an entire proprietary appliance. Those benefits become financially meaningful when the operator has enough scale, capability, and discipline to use them.
The central decision is therefore a comparison between two forms of cost. Traditional RAN embeds integration and accountability in a vendor”s price, sometimes alongside substantial platform markup and long-term lock-in. Open RAN exposes more of the integration work and places it on the operator, its partners, or a systems integrator. Carriers should begin radio swaps only after modeling both sides honestly. When continuous integration, automation, and lifecycle ownership are treated as first-class investments, Open RAN can deliver durable flexibility. When they are ignored, disaggregation may lower the equipment invoice while increasing the cost of running the network.


